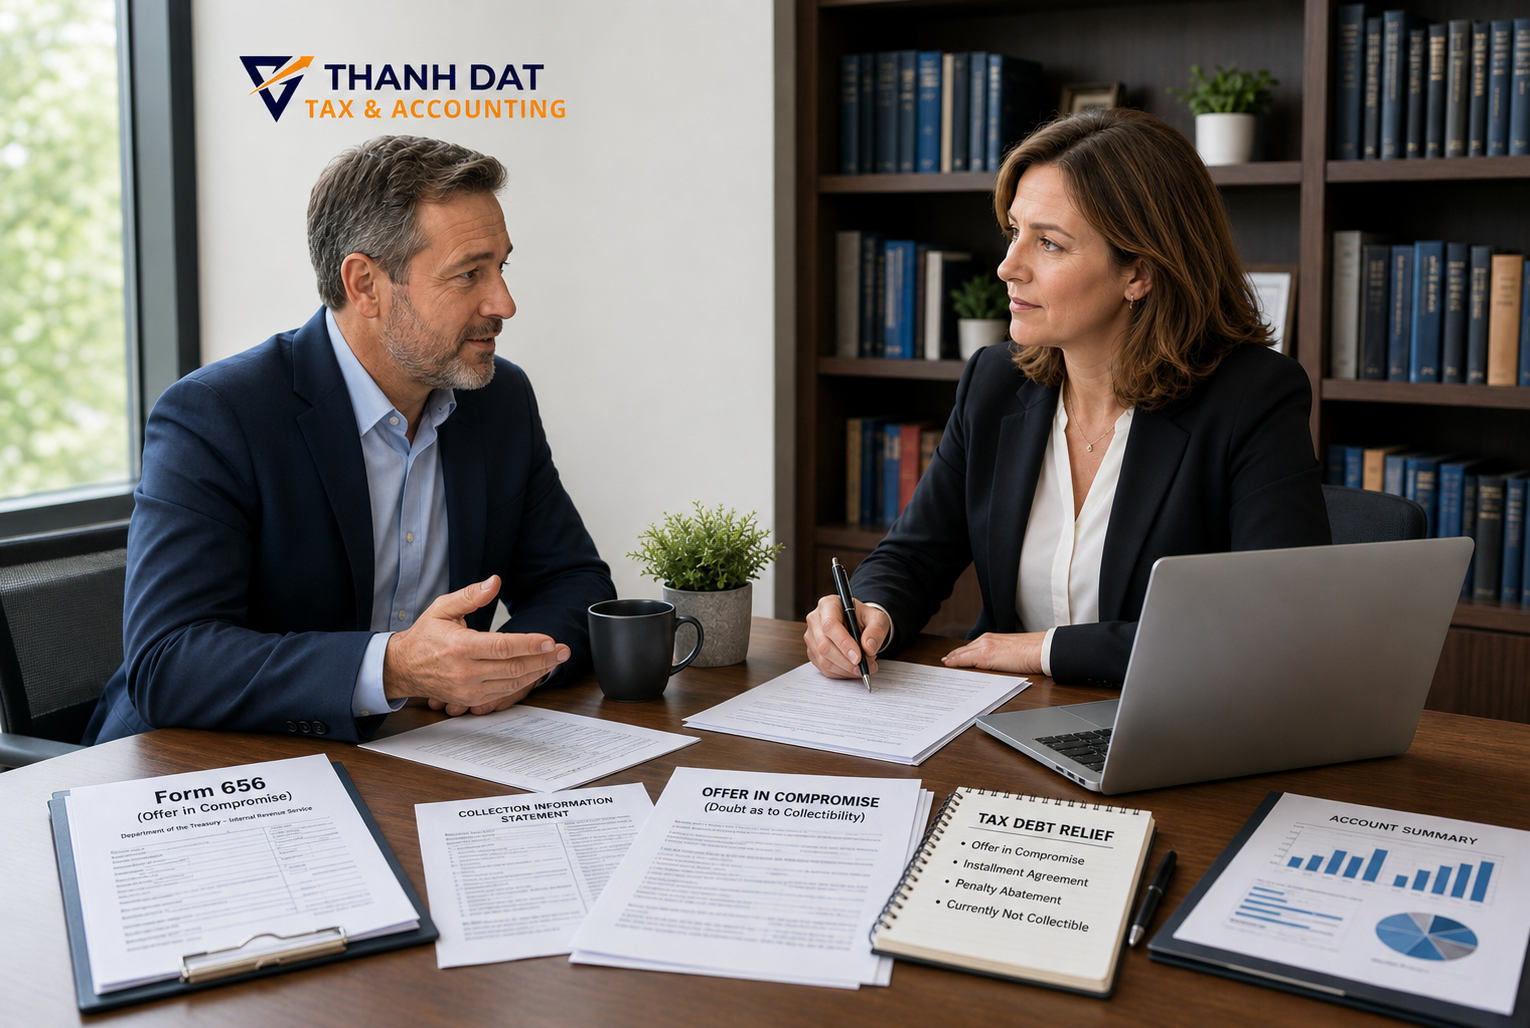

Opening your mailbox to find an unexpected IRS notice regarding unpaid balances or discrepancies can instantly trigger severe anxiety and financial distress. When tax debt accumulates beyond your financial capacity, attempting to navigate federal tax authorities alone can lead to severe penalties, wage garnishments, or bank levies. For taxpayers facing overwhelming tax liabilities, securing expert IRS Audit help is often the first critical step toward assessing eligibility for an Offer in Compromise (OIC)-the gold standard program for federal tax debt relief.
1. Qualifying for an Offer in Compromise and Eligibility Criteria
Before submitting a settlement request to the government, you must thoroughly evaluate whether your current financial status aligns with strict statutory requirements:
- Demonstrating Reasonable Collection Potential: The IRS calculates your minimum offer amount using a precise formula based on your total net asset equity combined with your projected future disposable income over a specific timeframe.
- Fulfilling Strict Compliance Prerequisites: You cannot apply unless all required past tax returns are properly filed and current-year estimated tax payments or wage withholdings are completely up to date.
- Evaluating Financial Hardship Thresholds: Applicants must provide clear proof that paying the full balance owed would either cause immediate insolvency or prevent them from meeting basic necessary household living expenses.
- Excluding Active Bankruptcy Cases: Taxpayers currently involved in open bankruptcy proceedings are legally disqualified from applying for a federal tax settlement until their bankruptcy case is formally closed or dismissed.
2. Key Settlement Pathways and Official Resolution Options
Understanding the specific mechanisms of federal tax debt relief helps establish an effective resolution strategy tailored precisely to your current financial capacity:
- Offer in Compromise (Doubt as to Collectibility): Settles tax liabilities for significantly less than the full balance owed when your verified income and assets cannot cover the total debt before the statutory collection period expires.
- Offer in Compromise (Doubt as to Liability): Resolves disputed tax assessments where a legitimate legal or factual error occurred during a prior examination, requiring targeted IRS Audit help to prove the tax was miscalculated.
- Offer in Compromise (Effective Tax Administration): Resolves tax debt when the assessment is legally correct and assets exist, but full payment would cause exceptional economic hardship or gross unfairness due to extraordinary medical or personal circumstances.
- Partial Payment Installment Agreement: Establishes structured, affordable monthly payments based strictly on verified disposable income when a lump-sum settlement offer is not currently feasible.
3. Procedural Mistakes and Hidden Risks in Self-Representation
Navigating complex collection guidelines and technical codes without specialized representation frequently leads to severe operational and financial setbacks:
- Miscalculating Allowable National Standards: Relying on actual household expenses rather than strict IRS Collection Financial Standards often results in inflated disposable income calculations and immediate offer rejections.
- Unintentional Extension of Collection Timelines: Submitting an unviable or incomplete offer automatically pauses the 10-year statutory period for the IRS to collect tax debt, effectively giving the agency more time to collect later without resolving your debt today.
- Disclosing Non-Exempt Financial Assets: Unrepresented individuals often unnecessarily disclose liquid assets or prospective income sources that prompt revenue officers to initiate immediate enforcement actions rather than consider settlement options.
4. Strategic Advantages of Professional IRS Negotiation and Representation
Enlisting a credentialed practitioner-such as an Enrolled Agent, CPA, or tax attorney-provides essential legal protections and technical guidance throughout the IRS negotiation:
- Establishment of Legal Power of Attorney: Filing Form 2848 transfers all verbal and written communications directly to your representative, ending direct enforcement contact and high-pressure interviews.
- Optimization of Financial Statements: Representatives meticulously review Form 433-A (OIC) to present your assets, income, and necessary living expenses in the most favorable light compliant with federal guidelines.
- Administrative Appeals and Penalty Abatement: If an initial offer is wrongfully rejected, your specialist can file formal protests with the IRS Independent Office of Appeals or negotiate structured penalty relief.
Conclusion
The small business tax deductions and credits 2026 provide powerful opportunities to reduce your tax burden and improve financial efficiency. With proper planning, accurate tracking, and expert guidance, you can maximize every available benefit.
👉 Contact Thanh Dat Tax today to make the most of your small business tax deductions and credits 2026 and start saving with confidence.
Thanh Dat Tax & Accounting – Professional Tax & Accounting Services
📍 2520 Beacon Ave S, Seattle, WA 98144.
📞 Phone: 206 483 9729
📧 Email: info@thanhdattax.com